Card 1 of 6 — Illustration for: ASML profit beats; customers now discussing 2030 orders
ASML Earnings: Demand Visibility Extends to 2030
ASML reported profits beating expectations and noted customer interest in placing orders through 2029 and 2030, signaling strong long-term demand.
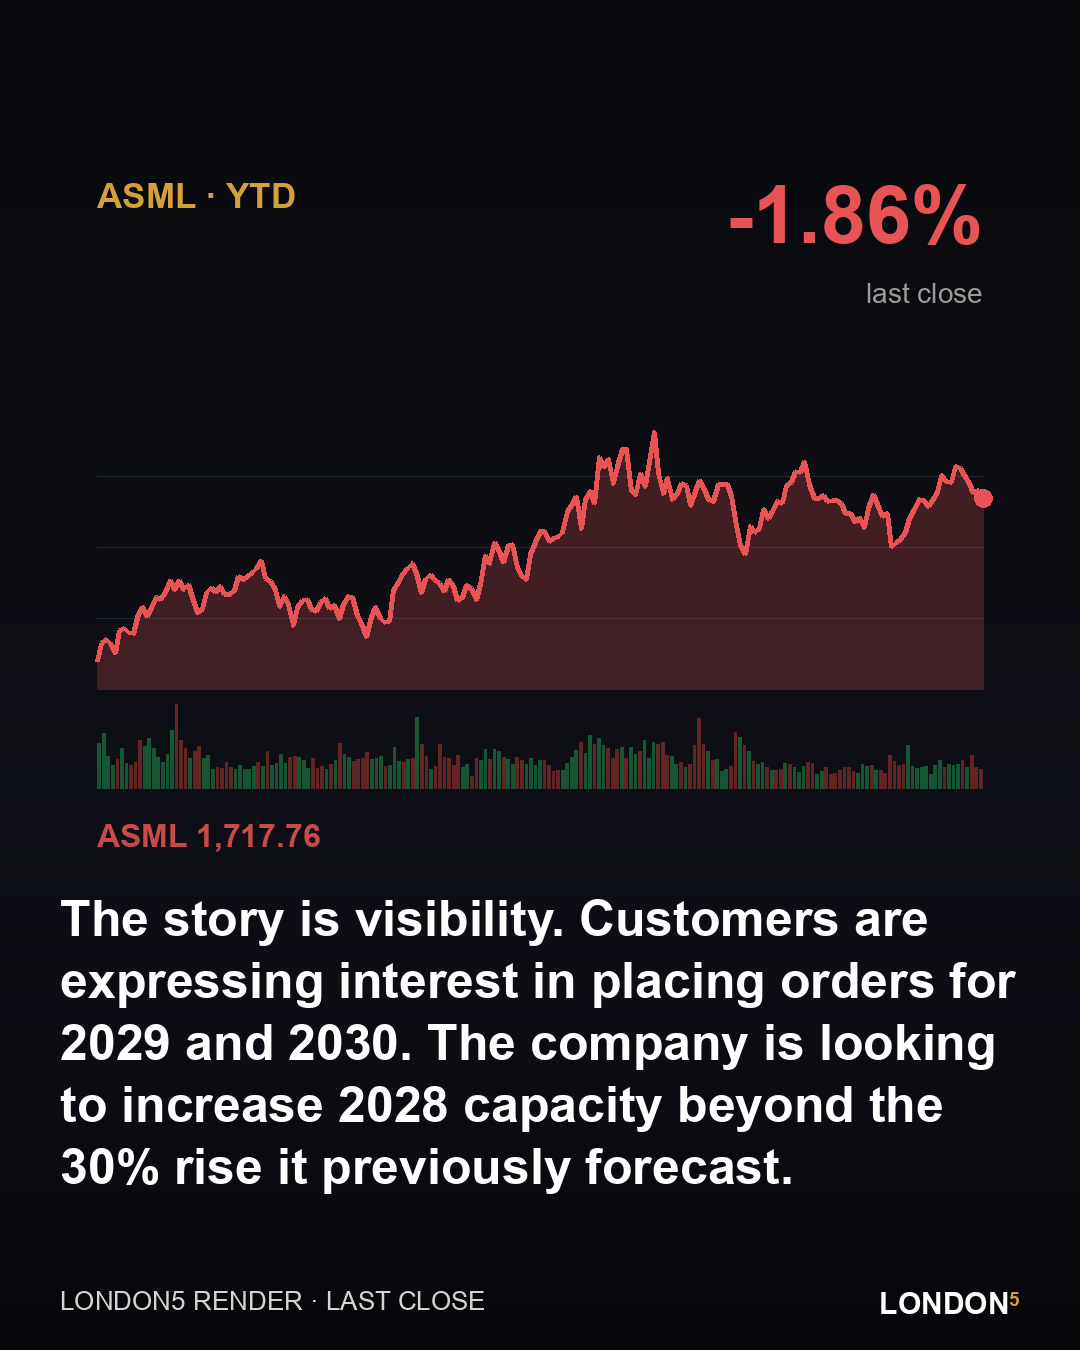
ASML reported third-quarter profits that exceeded market expectations, yet the narrative for investors lies beyond the immediate quarter. The company disclosed that some customers are expressing interest in placing orders for 2029 and 2030, offering a rare glimpse into long-term demand visibility. This development comes as ASML seeks to increase its 2028 capacity beyond the 30% increase it had previously forecast.
The Dutch chipmaker, which holds a monopoly on extreme ultraviolet (EUV) lithography machines, stated that current supply planned for 2027 and 2028 will not fully meet customer demand. CEO Christophe Fouquet noted that customers continue to increase their short- and medium-term equipment demand forecasts, driven primarily by their views on the size and duration of AI-related investments. In response to this visibility, some clients are now discussing orders extending into 2030.
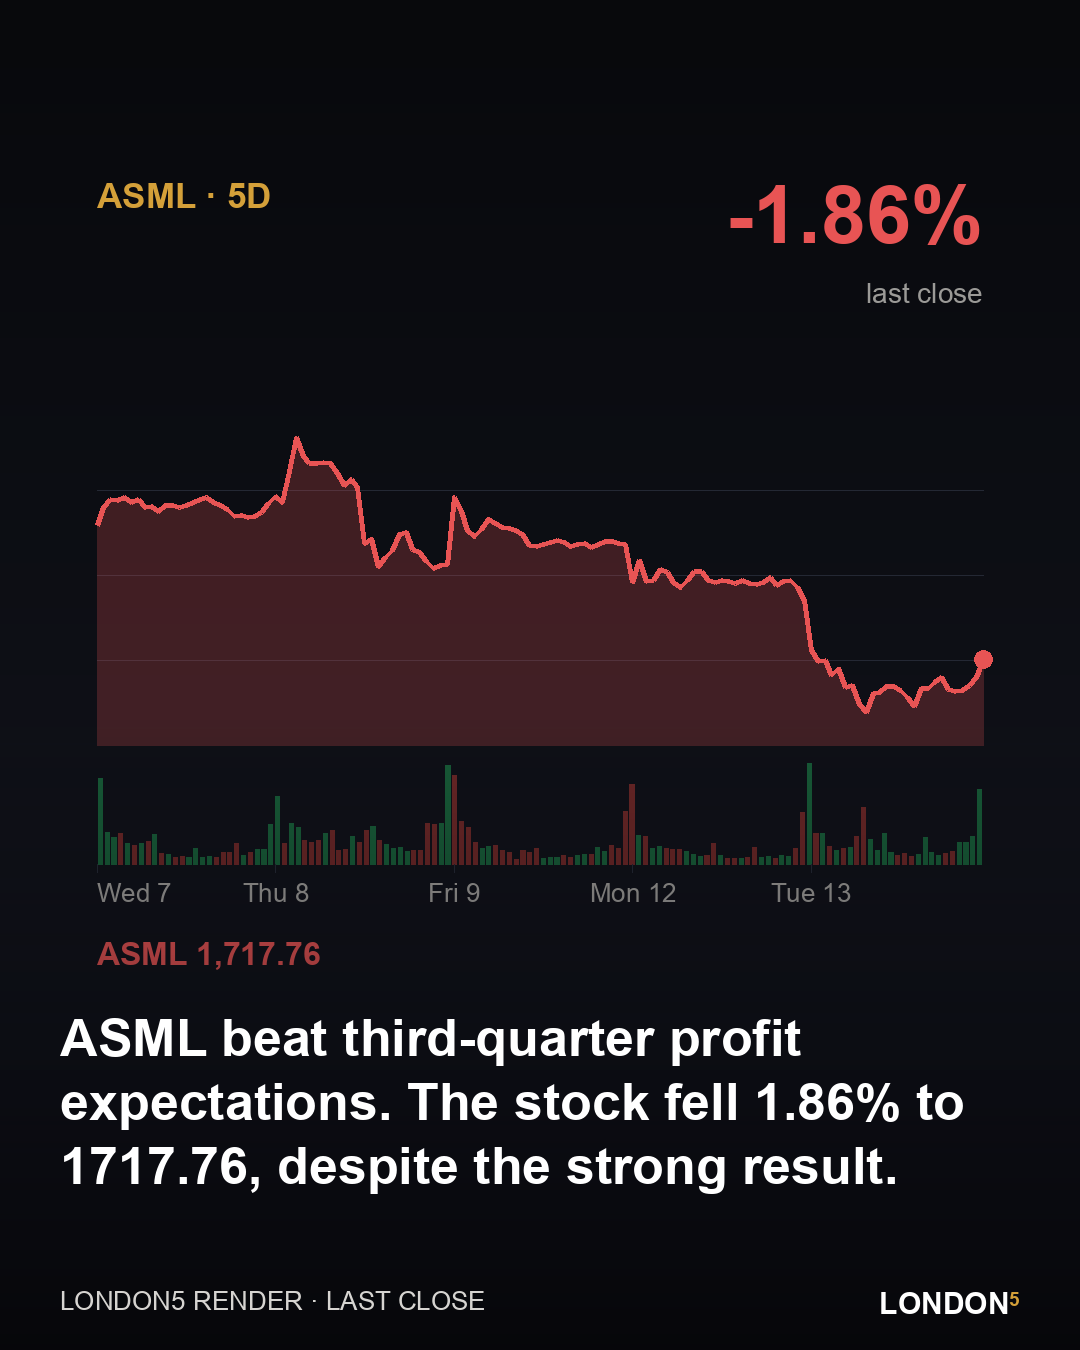
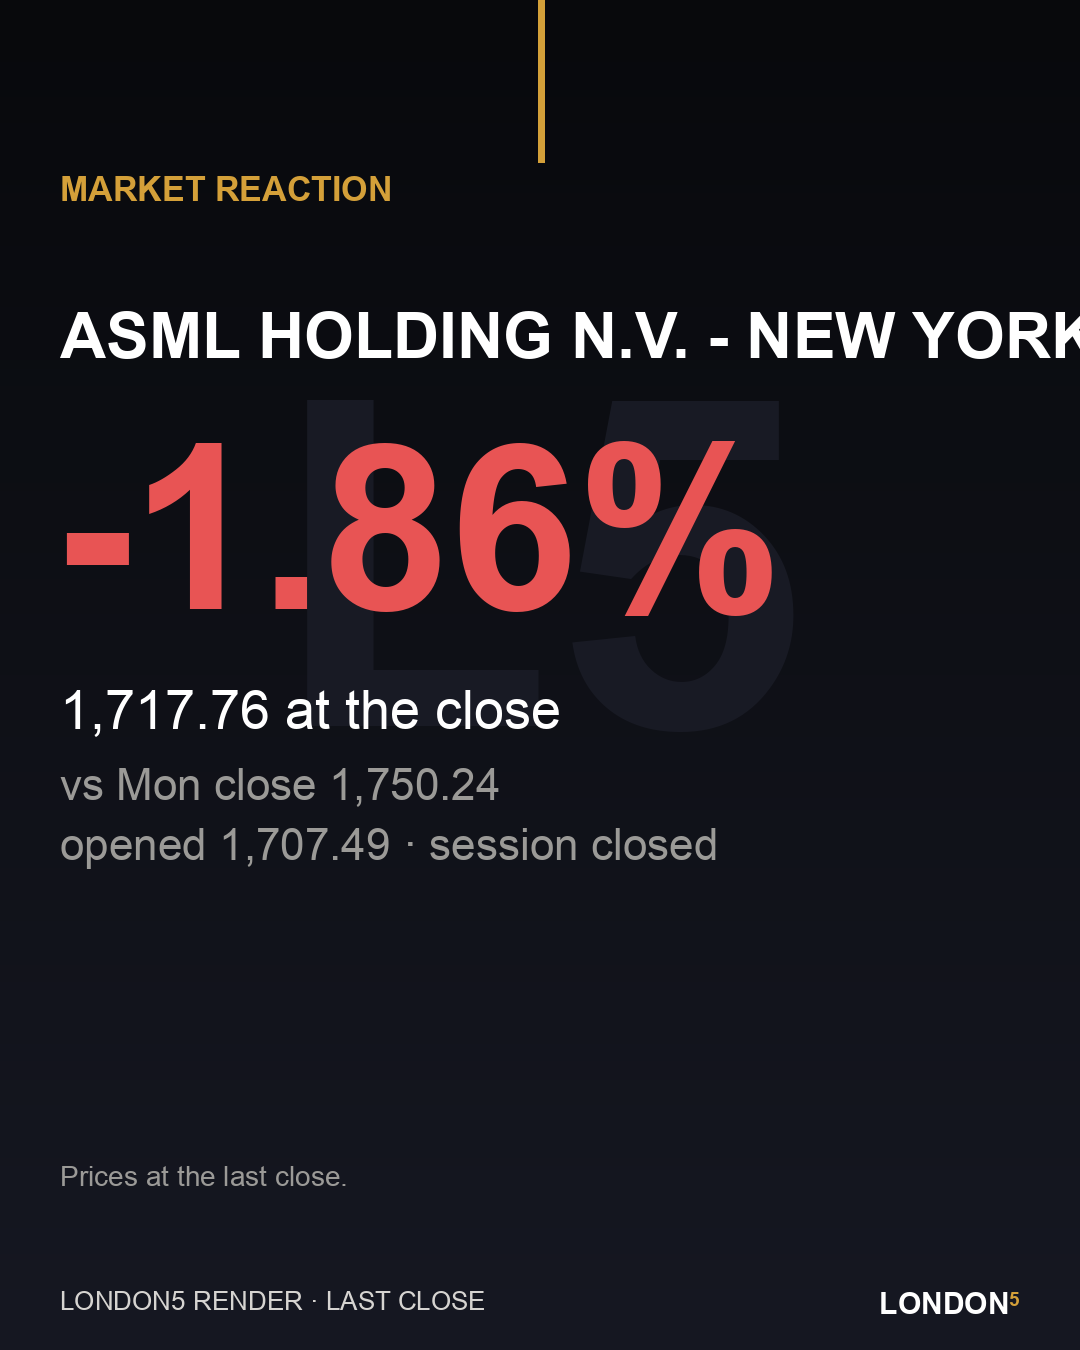
Financially, ASML narrowed its full-year revenue forecast, expecting net sales between 44 billion euros and 45 billion euros ($49.3 billion to $50.4 billion). This raises the previous lower end of 43 billion euros. For the fourth quarter, the company expects net sales between 14.2 billion euros and 15.2 billion euros, with the upper end ahead of LSEG consensus estimates. Despite the strong guidance, shares fell 1.86% to 1717.76, a reaction that may reflect profit-taking after a 56% rally this year.
The strategic landscape remains complex. While Samsung and TSMC have committed to using ASML’s High NA EUV machines, reports suggest an unnamed Chinese company has begun manufacturing an immersion deep ultraviolet (DUV) lithography machine. Although DUV is less advanced than EUV, China’s ramp-up of domestic semiconductor supply chains poses a potential challenge to European and U.S. dominance. ASML remains restricted from selling certain tools to China, adding a geopolitical layer to its growth story.
Our read: The immediate stock reaction is a distraction from the structural reality. When the sole producer of a critical tool reports that customers are placing orders two to four years out, the constraint is no longer demand but manufacturing capacity. The 30% capacity increase for 2028 is likely a floor, not a ceiling. The monopoly is under pressure from China’s DUV efforts, but EUV remains the bottleneck for the most advanced chips. The long-term demand picture is clearer than it has been in years.
Source · cnbc ↗ · Cards · 6 · 2 min read
How this was made. Spotted by the London5 Watchtower and written, pictured and rendered by London5 agents at 06:53; approved in the Régie by a human; published here at 07:35 London. Simulated results — not investment advice.